“How do I pay my mortgage off sooner?”
You’ve probably thought about making bigger repayments. Cutting back on idle subscriptions and memberships. And funnelling a bonus, tax return or any unexpected money into your mortgage account.
All useful.
But if you already own a home and you’re thinking about investing in property, there’s another question worth asking: Could an investment property help me pay off my mortgage faster?
The short answer? It can.
We sat down with Investor Assist’s finance partner, Adam Brink from Resolve Finance, to understand how an investment property could take the pressure off your home loan.
“An investment property can form part of your strategy to pay down your home loan sooner. This can include positive cash flow, capital growth, and possible tax deductions.”
Lever 1: Positive cash flow
Your investment property earns rent. Once you cover ongoing property expenses, any surplus has somewhere useful to go.
Adam explains: “Positive cash flow exists if your rental income exceeds the ongoing expenses for the property (maintenance, interest and loan repayments). You can then use this additional cash to increase your offset balance or reduce your home loan.”
And here’s where it gets interesting.
Putting extra money against your home loan doesn’t just reduce the balance by that amount. Adam says those additional funds can also reduce the interest charged, “which results in more of your loan repayment being used to reduce the loan balance further.”
In other words, less interest means more of your future repayments can go towards the loan itself.
Lever 2: Capital growth
Here you’ll play the longer game. Instead of relying entirely on what you can find in the household budget each month, you potentially have another asset building in value behind the scenes.
Adam says you can simply think of capital growth as “the value of your property increasing.” He explains that “over the medium to long term a well-chosen property can increase in value” and that, if you later sell, “the profit/capital gains” could be used as a lump-sum payment on your home loan.
Down the track, that could make a much bigger dent in the mortgage than sporadic payments.
Lever 3: Possible tax deductions
Tax deductions might not spark the same joy as watching the mortgage balance drop. But it could free up more cash.
Adam says: “An investment property may allow a borrower to claim certain tax deductions, which can assist in freeing up funds that can be directed towards your offset or home loan.”
What you may be entitled to depends on your circumstances, so work this through with your accountant or financial adviser rather than making assumptions.
Lever 4: Every extra dollar works harder than you think
Extra money counts, often more than you may expect. “People often underestimate the impact of paying even a little extra,” Adam says.
Here’s why: “If your minimum repayment is $1,000 per month over 30 years, doubling that repayment doesn’t necessarily mean you’ll halve the loan term to 15 years. You could pay it off considerably sooner because every extra dollar reduces the balance on which future interest is calculated.”
This information does not consider your personal financial circumstances, and you should seek advice from your Accountant or Financial Planner. Finance options are available through Resolve Finance Solutions PTY LTD trading as Resolve Finance ABN 65 079 545 378 (Australian Credit Licence 385487).
Before you mentally delete the mortgage…
The bigger idea behind these four levers is that your salary doesn’t always have to do all the heavy lifting. An investment property can become part of a broader strategy to reduce your home loan.
But, let’s be clear: buying an investment property and assuming your mortgage will magically disappear is false.
Rental surplus, freed-up tax funds or a lump sum from capital growth can help. But before acting, Adam recommends getting advice from “your accountant, financial adviser and your mortgage broker. Because all investment strategies include a level of risk and things change.”
Could these levers help you pay your mortgage off sooner?
Let’s map it out.
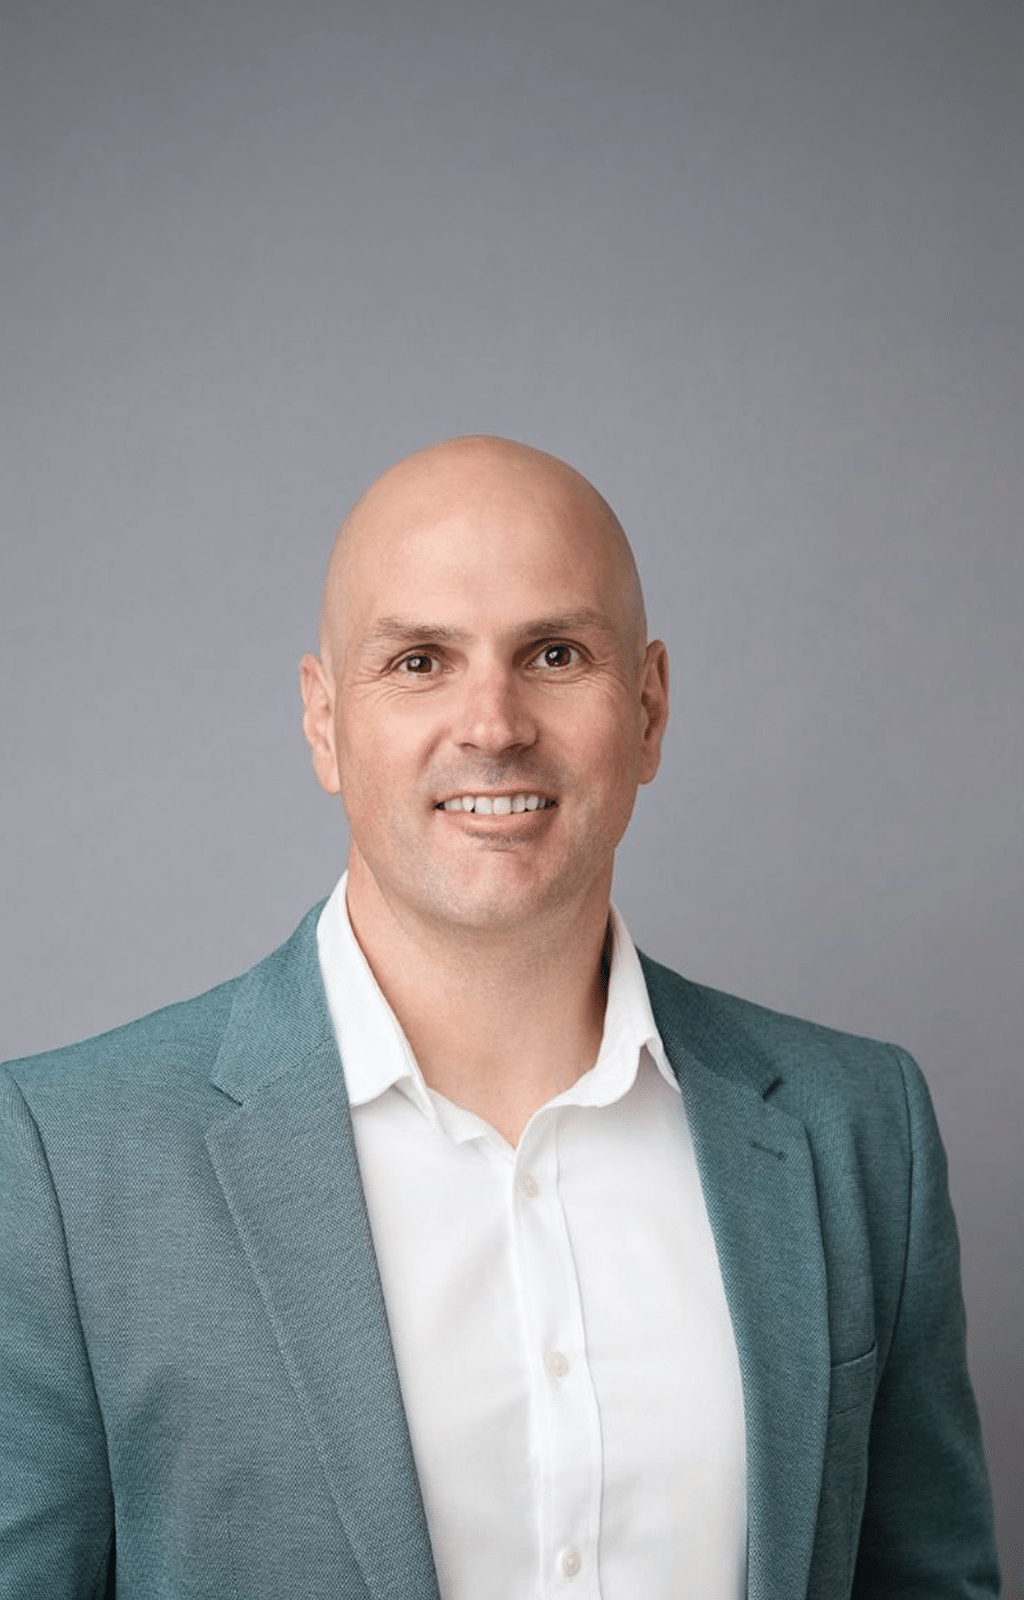
About Adam Brink
With over 25-years of expertise in banking and finance, Adam is the Principal Owner and Lending adviser at Resolve Finance Caroline Springs, where he combines a deep industry knowledge with a genuine care for his clients.